Medicare
Is Your Medicare Advantage Plan Ending in 2027? How to Check and What Happens Next
Non-renewal letters for 2027 are due by October 2, and what you do in the weeks after decides whether you start January with full coverage or with gaps.
 Margaret Linwood
Updated Sep 22, 2026 · 11 min read
When an insurer decides not to offer a Medicare Advantage plan next year, federal rules make it tell members by mail at least 90 days before the plan ends. For a plan that stops on December 31, the letter is due by October 2. If your plan is going away in 2027, the notice is either in your mailbox now or about to be.
This used to be rare. Researchers at Johns Hopkins, writing in JAMA in February, found that from 2018 through 2024 about 1% of Medicare Advantage members a year were forced out of their plan because it closed or pulled out of their area. In 2025 it was 6.9%. For 2026 they estimated 10%, about 2.9 million people. In Vermont it was 92% of members, twelve states topped 20%, and rural areas took the worst of it.
Nobody has the 2027 count yet. It'll come after the federal government publishes next year's plan data and analysts add it up. Several big insurers have already said in public, including on calls with investors, that they're dropping more plans and leaving more counties for 2027.
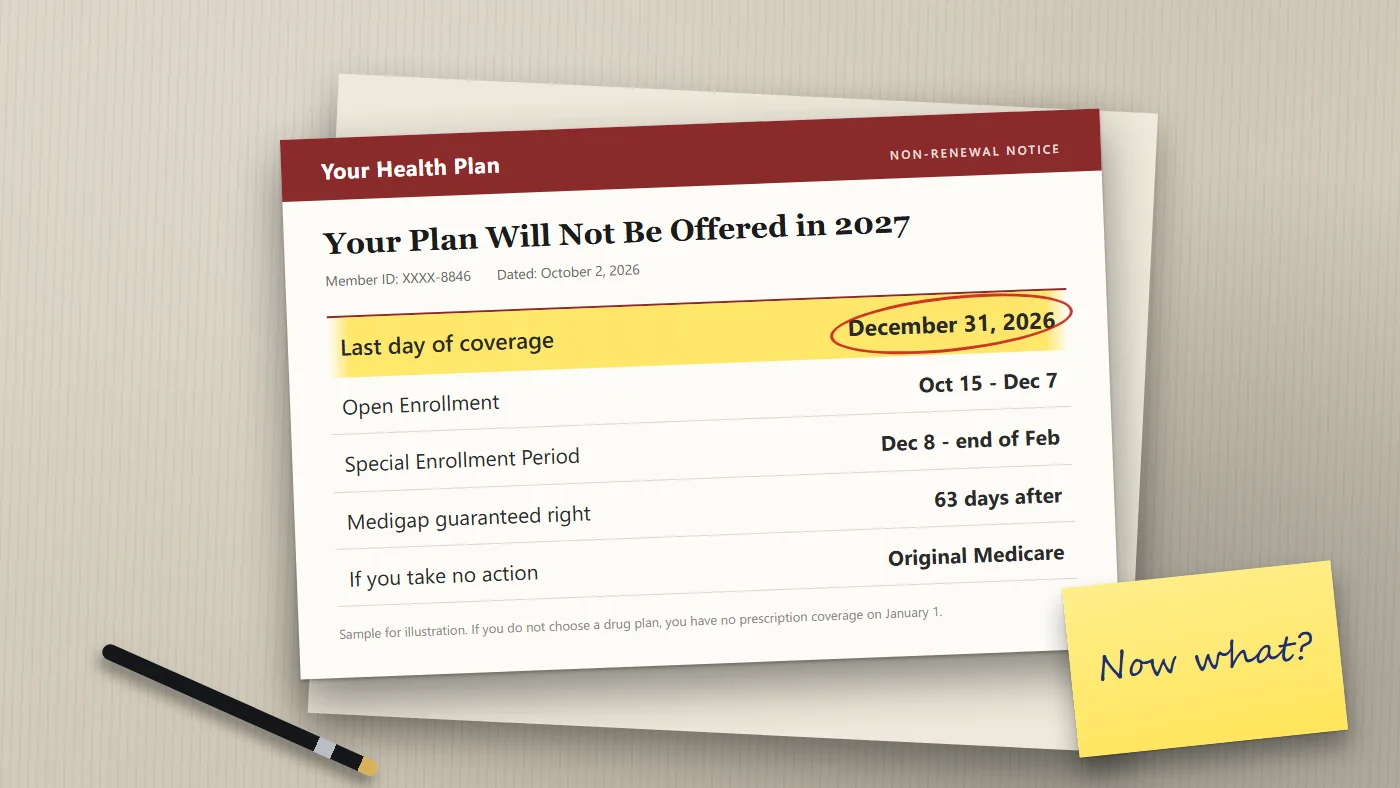
If your plan's on the way out, two things are true at once. Your coverage works normally through December 31, so nothing changes at the doctor's office this fall. And if you do nothing at all, you'll start January in Original Medicare with no drug plan and no yearly limit on what you pay.
There's also something useful buried in that letter. It hands you a right most Medicare Advantage members don't have, and the right comes with a clock.
Three ways to check, fastest first
Call the number on your plan card. Ask one question: "Is my plan, in my county, being offered in 2027?" Give them the plan name and your ZIP code. It takes a few minutes, and you don't have to wait for the mail.
Look at the mail from your plan. A plan that's continuing sends an Annual Notice of Change by September 30. A plan that's ending sends a non-renewal notice. It says in plain words that your coverage ends December 31, lists other plans in your area and explains your special rights. The real one carries your plan name and member details. Be wary of look-alike mailers from sales agencies.
Check the Medicare Plan Finder. Starting October 1, Medicare.gov shows the plans available in your ZIP code for 2027. If yours isn't listed, or isn't listed for your county, you've got your answer.
"Ending" comes in three versions, and they don't work the same way.
- The plan is terminated. The insurer stops offering it anywhere. You get the rights described below.
- The plan leaves your county. It carries on elsewhere, but your area is cut from its service area. For you, the effect and the rights are the same as a termination.
- The plan is merged into another one. The insurer moves you automatically into a different plan it sells. You're not left without coverage, but the new plan can have a different network, drug list and out-of-pocket maximum. KFF found that for 2026, on top of 2.6 million people in terminated plans, another 1.3 million were in plans being consolidated. Your Annual Notice of Change will name the new plan. Read it like a plan you've never seen.
For 2026, about 1 in 10 Medicare Advantage members, roughly 2.9 million people, were forced to find a new plan. From 2018 through 2024 the rate averaged about 1 in 100.
What happens January 1 if you do nothing?
Medicare.gov puts the default in one sentence: you'll be enrolled in Original Medicare if you don't join another Medicare Advantage plan before your current plan ends.
Original Medicare is solid coverage, and most doctors and hospitals in the country take it. The default version has two holes, though. It doesn't include Part D, so you'd have no prescription coverage unless you pick a drug plan yourself. And it has no annual cap: after the Part B deductible, $283 in 2026, you owe 20% of most outpatient bills with no upper limit, and the hospital deductible is $1,736 per benefit period.
Say you land in Original Medicare by default and need a $4,000 outpatient procedure early in the year. Using 2026 numbers, you'd pay the $283 deductible plus 20% of the remaining $3,717, about $743, for roughly $1,026 in all. Nothing caps the next bill either.
Going without drug coverage can cost you later, too. If you go 63 days or more without Part D or other creditable coverage, a late enrollment penalty gets added to your drug premium for as long as you have Part D.
All of it's avoidable. You've got three real options, each with its own deadline, and one of them opens a door that people leaving Medicare Advantage usually find locked.