When a life insurance policy lapses, the owner gets nothing. Every premium paid over 20 or 30 years is gone, and the insurer is off the hook for the death benefit. If the policy has cash value, surrendering it gets you that amount, minus any surrender charge, and lets the insurer off the hook the same way.
There's a third way out that most policy owners have never heard of. In 43 states and Puerto Rico, a life insurance policy is treated as property you can sell to a licensed buyer. The buyer pays you a lump sum, takes over the premiums and collects the death benefit when you die. It's called a life settlement.
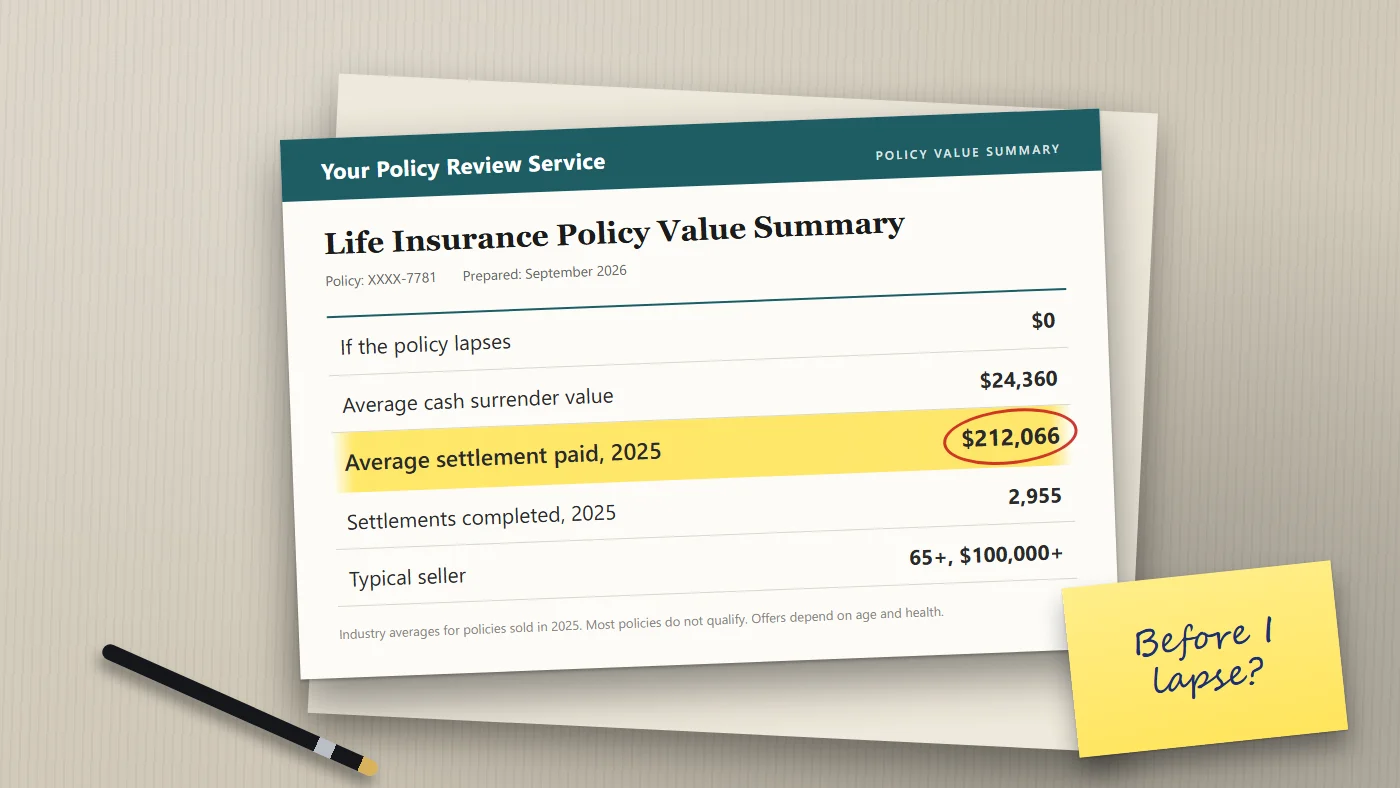
The numbers can be striking. The Life Insurance Settlement Association, the industry's trade group, reports that its members completed 2,955 of these deals in 2025 and paid policy owners $626.6 million. The average payout was $212,066. The average cash surrender value of those same policies? $24,360. Sellers got almost nine times what their insurers would have paid.
Hold that number loosely. It comes from the buyers' own association, and it describes the policies buyers wanted: big ones, on older people, often in poor health. Most policies won't qualify. By the association's count, more than 9 million policies are surrendered or lapse every year, and fewer than 3,000 get sold. But if yours might qualify, you'll want to know before you stop paying, because a lapse can't be undone.
Who can sell, and who can't
Buyers are investors. They're estimating how long they'll pay premiums before they collect, and that shapes who gets an offer.
Going by the settlement association's guidance for policy owners, buyers most often want an insured who's 65 or older and a death benefit of $100,000 or more. Younger people with a serious illness may qualify too. Universal life, whole life and even term policies can be sold, though buyers usually want a term policy that can still be converted to permanent coverage.
Your state also sets a waiting period after the policy's issued: two years in 30 states, five years in 11 and four years in Minnesota. Most states make exceptions for events like terminal or chronic illness, divorce or retirement.
In practice, the strongest candidates tend to be in their 70s or 80s, with health that's declined since the policy was issued and premiums high enough to hurt. A healthy 66-year-old with a $150,000 whole life policy may get no offer at all, or one below the cash value.
What do settlements actually pay?
There's no price list. Each offer is built from your life expectancy, which the buyer estimates from your medical records, plus the premiums needed to keep the policy in force and the return the buyer wants.
So why would a stranger pay more than your own insurer? The insurer's surrender value comes from a formula in the contract that ignores your health entirely. A buyer looks at the same policy and sees a $500,000 check at some point in the future, minus all the premiums it'll have to pay until then, and if your health has gotten worse, that check is closer and the policy is worth more. It works the other way too. Likely to live another 20 years? The premiums eat the value, and the offer shrinks or disappears.
Aggregate data gives a rough sense of scale. In 2023, the association's members bought policies with $4.67 billion in death benefits and paid owners $842 million, or about 18 cents per dollar of face value. That's an average across very different policies, though: the older and sicker the insured, the bigger the share of face value a buyer can afford to pay, and for a healthy person in their late 60s the number can be close to nothing.
In 2025, policy owners who sold through settlement association members received an average of $212,066. The average surrender value of those policies was $24,360. A lapsed policy pays $0.
Say you're 78, with a $500,000 universal life policy. The cash surrender value is $30,000, and keeping the policy going takes $18,000 a year in premiums. Your choices, if a buyer offered that 18% figure:
| What you do | What you get now | What your heirs get | What you keep paying |
|---|
| Stop paying and let it lapse | $0 | $0 | $0 |
| Surrender to the insurer | $30,000 | $0 | $0 |
| Sell at 18% of face value | $90,000, before taxes | $0 | $0 |
| Keep the policy | $0 | $500,000 | $18,000 a year |
Don't skip the last row. If you can afford the premiums, or your kids can, keeping the policy is often the best financial outcome for the family, since an investor offering $90,000 expects to come out well ahead. A settlement makes sense when keeping the policy truly isn't possible.
Before you get there, your insurer may have in-between options it won't mention unless you ask. And there's a tax bill that catches a lot of sellers off guard.
Eight steps, in order
- Ask your insurer for an in-force illustration. It's a projection showing the current cash value, the surrender charge and the premium needed to keep coverage to age 95 or 100. You'll need it for every decision after this, and any buyer will ask for it.
- Ask about the in-between options. You may be able to lower the death benefit to cut the premium, or take a reduced paid-up policy with no more payments. You could use the cash value to cover premiums for a few years, or borrow against the policy. If you're seriously ill, ask whether the policy has an accelerated death benefit that pays part of the face amount while you're alive. Each of these keeps some death benefit for your family.
- Check your state's rules. Your state insurance department licenses settlement brokers and providers, and its website shows who holds a license and what disclosures you're owed. A few states don't regulate these sales at all. That's a reason for extra care, not a reason to skip the check.
- Decide how you'll get bids. A settlement provider is the buyer. A settlement broker represents you, shops the policy to several providers and is paid a commission out of the sale. Going straight to one provider is simpler, but you'll see one offer. Either way, you want several competing bids.
- Authorize the medical review. You'll sign releases so buyers can get your records and order a life expectancy report. The association puts the whole process at three to five months from application to payment.
- Get every offer in writing. Many regulated states require that you see all offers and counteroffers, and many require the broker's pay to be disclosed. Ask for the commission in dollars. It comes out of your proceeds, so a lower commission on the same bid means more for you.
- See a tax professional before you sign. The next section explains why. Also ask how a lump sum would affect Medicaid, Supplemental Security Income or any other benefit with income or asset limits. Many states require that sellers be warned about this, because a settlement can end eligibility.
- Read the contract for three things. The money should sit in escrow and be paid when ownership transfers. Find your right to cancel, which state law usually gives you for a short window. And look for the buyer's right to contact you or your doctor in later years to check on your health, which is normal and shouldn't come as a surprise.
The tax bill sellers don't see coming
A death benefit is generally free of income tax. Money from selling a policy isn't.
The IRS laid out the rules in Revenue Ruling 2009-13 and updated them in Revenue Ruling 2020-05 after the 2017 tax law. The proceeds come in three layers. Up to your basis, meaning the total premiums you paid, it's tax free. Above your basis and up to the policy's cash surrender value, it's ordinary income. Anything above the cash surrender value is a capital gain.
The IRS example uses round numbers. An owner paid $64,000 in premiums on a policy with a $78,000 cash surrender value and sold it for $80,000. The gain was $16,000: $14,000 of ordinary income and $2,000 of long-term capital gain.
Now run the 78-year-old from the table through it. If she'd paid $140,000 in premiums over the years, the $90,000 sale is below her basis and there's no taxable gain. If she'd paid $50,000, then $40,000 of the proceeds would be taxable, and because the $30,000 cash value sits below her basis, all $40,000 would be capital gain. The buyer reports the sale to the IRS on Form 1099-LS and the insurer reports your basis on Form 1099-SB. The IRS will have the numbers either way.
Different rules apply if you're terminally or chronically ill. A sale to a licensed viatical settlement provider can be treated like a death benefit and left out of income, fully for the terminally ill and, for the chronically ill, generally only to the extent the money goes to qualified long-term care costs. The definitions are strict. Get advice that fits your situation.
Risks and red flags
Your family gets nothing from the policy. Obvious, and still the thing people regret most. Tell your beneficiaries before you sell, not after.
You may not be able to replace the coverage. At your age and health, a new policy may not be available at any price.
The offer can change or fall through, since bids rest on medical records and a life expectancy estimate. If new records turn up or a second estimate comes in longer, a buyer may cut its price or walk away before closing. Keep paying premiums until the sale's done so the policy doesn't lapse while you wait.
Your medical information travels, too, because policies often get resold to other investors, sometimes more than once, so ask who'll hold your records after the sale and how they're protected.
Be wary of anyone who suggests buying a new policy just to sell it. That's stranger-originated life insurance, or STOLI. Twenty-nine states have laws that expressly ban it, and an insurer can challenge the policy and leave you tangled up in a fraud claim.
Be wary, too, of pressure, upfront fees or a single "take it today" offer. The settlement association says sellers generally have no out-of-pocket costs, and a legitimate buyer expects you to compare.
How do I get offers I can compare?
Online settlement calculators give a ballpark from your age, health and face amount, but treat the result as a reason to look further rather than a quote, because real offers only come after a buyer has read your medical records and paid for a life expectancy report.
If you go ahead, treat it like selling a house: a broker with a duty to you, several bidders and a written net figure will usually beat one conversation with one buyer. I'd ask every firm the same five things:
- Are you licensed in my state, and as a broker or a provider?
- How many buyers will see my policy?
- What's your compensation, in dollars?
- Who pays the premiums while we wait?
- What happens if I change my mind?
Then compare the best net offer against the step 2 options, after tax. For some owners a reduced paid-up policy or a smaller death benefit is the better answer, and asking costs nothing. If it's a term policy close to its conversion deadline, talk to buyers before that date. Once a term policy can't be converted, it usually has little or no resale value.
Before you stop paying
A policy you can't afford is still worth more than zero, sometimes well above the surrender figure on your statement. If you're past 65 with $100,000 or more of coverage, request the in-force illustration now and get at least one outside bid before the next premium due date on your statement.
This article is general information, not financial, legal, tax or medical advice.