Most cars built in the last several years carry their own cellular connection. It runs the app that locks your doors, the crash-response button and the maintenance alerts. It also sends data back to the manufacturer, and for years some of that data didn't stay there.
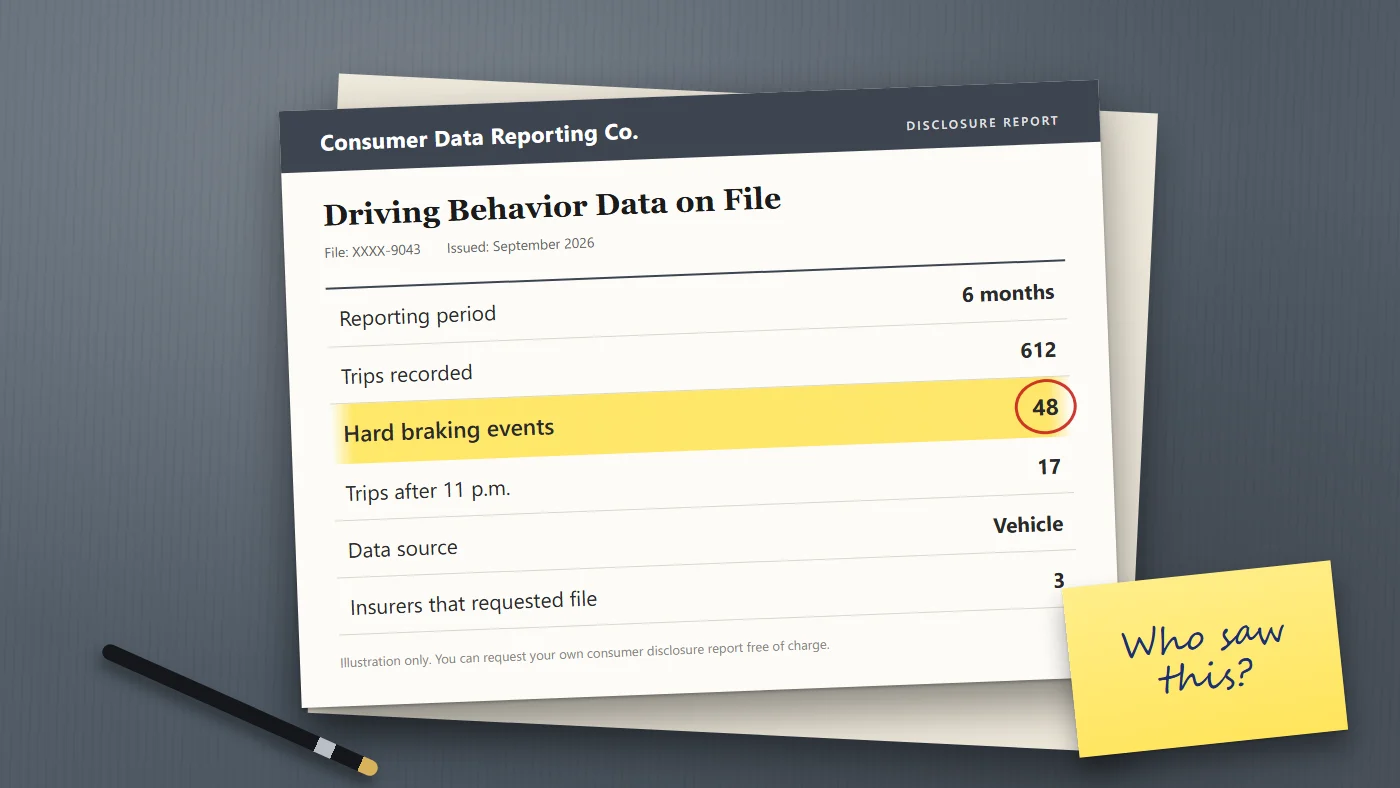
In January 2025 the Federal Trade Commission took action against General Motors and its OnStar unit. The agency said GM collected precise location and driving behavior from millions of vehicles, as often as every three seconds for some drivers, and sold it without clear consent. The events it logged included hard braking, late-night driving and speeding.
The buyers were consumer reporting agencies, the same kind of company that keeps your claims history. They packaged the data into driver reports, and according to the FTC, insurers relied on those reports to set rates and, in some cases, to deny coverage.
Plenty of drivers had no idea. The FTC called the enrollment process behind the feature doing the collecting, a program named Smart Driver, misleading. Some people didn't know they'd been signed up at all, and found out only when a premium went up or an application was turned down and an agent mentioned a report they'd never heard of.
Every 3 seconds: how often, the FTC says, location and driving data was collected from some vehicles. Texas, in a separate lawsuit, alleges the data of more than 1.5 million of its drivers was sold.
What's happened since
The FTC finalized its order on January 14, 2026. For five years, GM and OnStar can't disclose drivers' location or driving behavior data to consumer reporting agencies. For 20 years, they have to get your affirmative consent before collecting or sharing connected-vehicle data, let you get a copy of your data and ask for it to be deleted, and give you a way to turn off precise location tracking where the vehicle allows it.
States have moved too, each in its own way.
| Who acted | Against | What it says happened | Status as of September 2026 |
|---|
| Federal Trade Commission | GM and OnStar | Location and driving data collected and sold without clear consent | Final order, January 2026 |
| Texas Attorney General | GM | Driving data of more than 1.5 million Texans sold to companies serving insurers | Lawsuit filed August 2024, pending |
| Texas Attorney General | An insurer and its data subsidiary | Driving data gathered through software built into phone apps, covering more than 45 million Americans | Lawsuit filed January 2025, pending |
| Arkansas and Nebraska Attorneys General | GM and OnStar | Similar claims under state consumer laws | Lawsuits filed in 2025 |
| California Attorney General and privacy agency | GM | Location and driving data of hundreds of thousands of Californians sold to two data brokers from 2020 to 2024 | $12.75 million settlement announced May 2026, subject to court approval |
California's case adds two useful facts. The state says GM earned roughly $20 million nationwide from these sales. It also found that California drivers didn't see higher premiums from the data, because California law doesn't let insurers use driving data like this to set rates. Drivers in other states had no such protection.
Much of this surfaced in March 2024, when The New York Times reported that GM owners who'd asked LexisNexis for their files were finding page after page of their own trips, with start and end times, distances and counts of hard braking and speeding. Within weeks, GM said it had stopped sharing this data with the two brokers, LexisNexis and Verisk, and it later ended Smart Driver. Lawsuits are allegations until a court rules, and the companies dispute parts of them.
Why this still matters if you don't drive a GM
The collecting hasn't stopped. Nearly every automaker gathers driving and location data from connected cars, and what the enforcement actions changed is who the data can go to and what consent is needed first. Texas opened inquiries into several other automakers in 2024. California's privacy agency has fined Honda ($632,500, in March 2025) and Ford ($375,703, in March 2026) for making it too hard to opt out.
Your phone can do the job, too. Texas's case against an insurer's data company is about software tucked inside ordinary apps, such as ones for gas prices or family location, that allegedly logged how the phone moved while its owner drove. No connected car needed.
And a lot of driving data now reaches insurers with the driver's blessing. Usage-based insurance programs, the plug-in devices and phone apps that promise a discount for safe driving, are the legal, opt-in version of the same idea. About one in six insurance shoppers ended up buying one, according to J.D. Power's 2025 study. They can save money. Some can also raise your rate, which isn't always spelled out at sign-up.
So can your car record how you drive? Almost certainly. The better questions are whether a file with your name on it already exists, who's seen it and how to shut off the flow. Each one has a specific place to look.
Check whether a driving file exists
- Request your LexisNexis consumer disclosure report. LexisNexis Risk Solutions runs the C.L.U.E. claims database and also handled telematics data. The Consumer Financial Protection Bureau lists it among the specialty reporting companies that must give you a free report on request. Order it online at consumer.risk.lexisnexis.com, by mail, or by calling its consumer center at 1-800-456-6004. If driving data was reported, it'll typically show up as a telematics section listing trips and events like hard braking and rapid acceleration.
- Ask Verisk for your file as well. Verisk was the other broker named in the GM cases. It has reportedly left the driving-behavior data business for insurers, but you're still entitled to ask what it holds on you.
- Find the section that lists who pulled the report. A disclosure report shows which insurers requested your information and when, which tells you whether the file could have touched a quote.
- Request your data from the automaker. Every major manufacturer has a privacy request page or an option in its app. Ask for a copy of the personal data it holds and a list of the third parties it's shared with. Under the FTC order, GM has to honor these requests nationwide. For other brands, your rights depend on your state.
- Dispute anything wrong. These are consumer reports under the Fair Credit Reporting Act. If the file shows trips you didn't take, say from a car you sold, you can dispute it, and the company has to investigate.
Reports by mail can take a couple of weeks. They're free, so be wary of any site that wants a fee to fetch them for you.
Turn off the sharing
There's no single switch. You'll have to work through the layers.
The car's app. Open the manufacturer's app and look under Privacy, Data Sharing or Connected Services. Turn off anything described as driving score, driver feedback, smart driver, driving insights or insurance offers, plus third-party data sharing if it's a separate toggle.
The car's screen. Many infotainment systems have their own privacy menu, with separate controls for location and data sharing. Some settings reset after a software update. Check again whenever the car updates.
A written privacy request. Through the automaker's privacy page, ask to opt out of the sale or sharing of your data and to limit the use of sensitive data such as precise location, and, if you want, ask for deletion. About 20 states now have consumer privacy laws that give residents some or all of these rights, and many automakers accept requests from any state. Asking costs nothing.
Your phone. Go through the location permissions and switch any app that doesn't need constant access from "Always" to "While Using" or "Never." Delete the apps you don't use anymore.
The dealer paperwork. Connected services often get switched on during delivery when you buy or lease. You can decline the trial or ask that data-sharing features be left off, and you should read before you tap "Agree" on that screen.
Consumer Reports' guide to these settings points out the trade-off. Turning off data collection entirely can also shut off features you may want: automatic crash notification, stolen-vehicle tracking, remote lock and start, roadside help through the app. For most drivers, I'd keep the safety services and refuse driver scoring and third-party sharing.
If your rate already went up
The notice is your starting point. When an insurer raises your price or turns you down because of a consumer report, federal law requires an adverse action notice that names the reporting company, and that tells you exactly which file to request.
Say the report holds driving data you never agreed to share. Dispute it with the reporting company, then tell the insurer in writing that the data's under dispute and ask to be re-rated without it.
Complaints come next. Three places take them: your state insurance department, your state attorney general's consumer protection office, and the FTC at ReportFraud.ftc.gov.
Then get new quotes. Not every insurer bought this kind of data, and one that never saw the file will rate you on your actual record. It's fair to ask each company straight out whether it uses third-party telematics or driving behavior data you didn't opt into. Keep the coverage limits identical across quotes, too, or you'll end up comparing policies instead of prices.
Should you ever share driving data on purpose?
For some drivers, yes. If you don't put many miles on the car, drive mostly in daylight and brake gently, a monitored program or a pay-per-mile policy can cut your premium. Retirees who no longer commute are often good candidates.
Just don't treat it as a sure thing. Maryland's insurance regulator looked at more than 260,000 telematics renewals in 2025. Most drivers came out ahead or even, with 31% getting a lower premium and 45% seeing no change at all. That still left 24%, about one in four, paying more (the breakdown was reported by MoneyGeek).
So before you enroll, pin down two things, in writing or in the program terms rather than the ad. The first is whether your rate can go up or only down. The second is what exactly gets recorded, including whether location is part of it, and whether that data is shared with or sold to anyone else. While you're reading, look for what happens to the data if you leave the program. If the terms don't say, that's an answer of its own.
Some states limit how much these programs can surcharge you, and your state insurance department's site will say whether yours does. Decided against monitoring? Say so when you shop. Plenty of well-rated insurers will quote you without it.
Mistakes to avoid
Plenty of people assume an older car means no data. It doesn't, if the car has a built-in cellular connection or you use the brand's app, and your phone can report the same things in any car at all.
Another common one is opting out in the app and stopping there. The written privacy request is what creates a record, and it's also what reaches data that's already been collected.
Then there are the services that charge to pull your reports for you. You don't need them, since the LexisNexis and Verisk disclosures are free by law.
And delivery day at the dealership, when you're tapping through every prompt to get the keys, is exactly when many drivers got enrolled in the first place.
Start with your state driving record, which you can already order and read. Then request the LexisNexis disclosure this week, and when it arrives, put the two side by side.
This article is general information, not financial, legal, tax or medical advice.