After a Car Accident: What to Say, What to Sign, and When the First Offer Is Too Low
Signing a release in the first week ends your right to claim more for bills that show up later, so the order in which you do things matters more than the amount of the first offer.
The crash wasn’t your fault. A few days later your phone rings, and a pleasant voice says they’re calling from the other driver’s insurance company. They want to ask a few questions, and they’d like to record the call. Sometimes, on that call or the next one, a dollar figure comes up, along with word that a check could go out this week.
There’s nothing improper about any of it. It just isn’t a courtesy call. The adjuster works for the company that’ll pay your claim, and in that very first conversation you can hand over the two things that shrink what it pays: your own words about fault and injuries, and your signature on a release.
Calls like this go out all the time. In 2024, there were about 6.18 million police-reported crashes in the United States, and about 2.42 million people were hurt in them (those are estimates from the National Highway Traffic Safety Administration). Most of those people had never handled a liability claim before, meaning a claim against the at-fault driver’s insurance. The adjuster on the other end of the line handles them every working day.
Four words cause more trouble than any others: “It was my fault.” People say them at the roadside and again on the phone, often out of politeness, often before they know what happened. The Illinois State Bar Association’s consumer guide is blunt about it: “Do not comment on the cause of the accident, and do not admit fault even if you think you were in the wrong.” You may be shaken and in no state to judge. Fault gets decided later, from the police report, photos, witness accounts and the damage to each car.
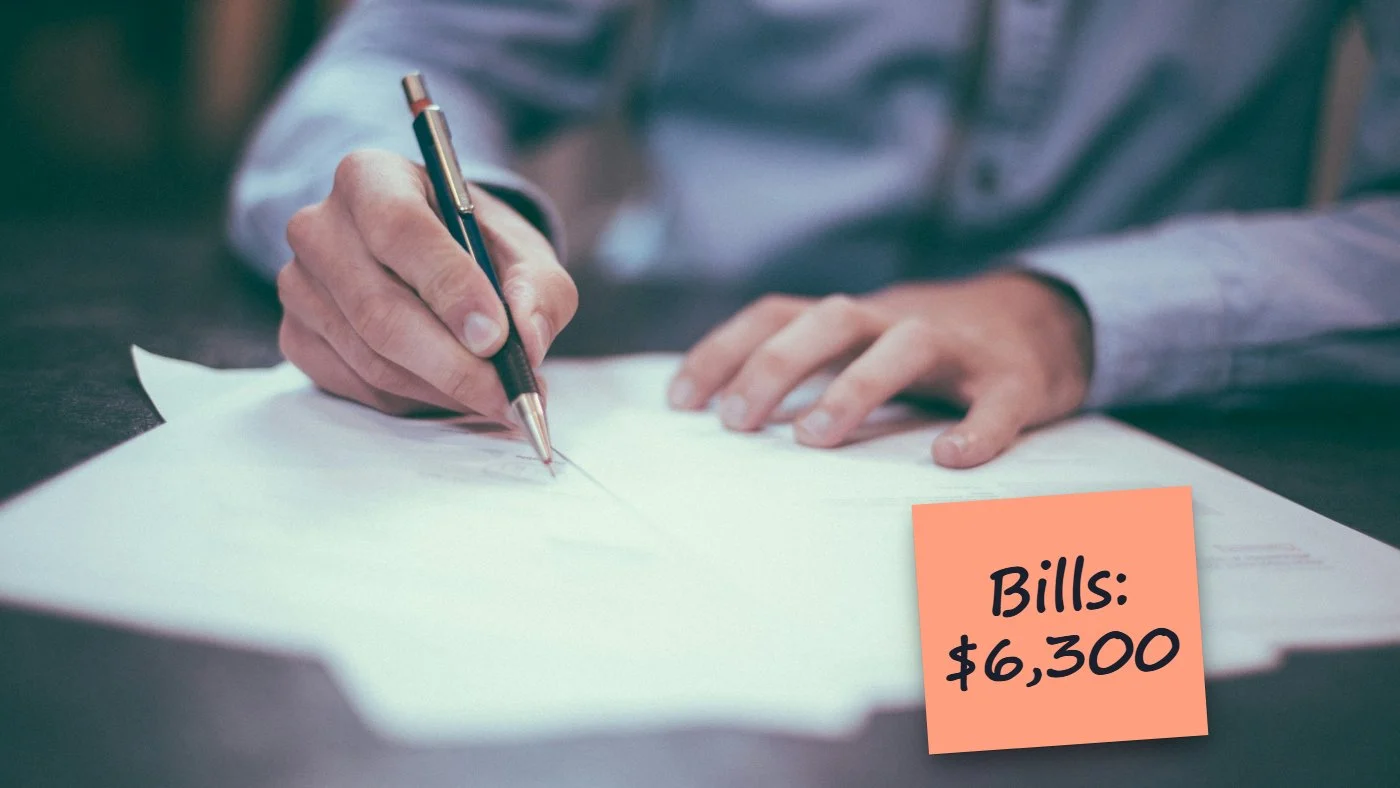
Here’s how a quick settlement goes wrong, in a made-up example. An adjuster offers $4,000 a week after a rear-end collision, and the driver signs. Over the next month the bills trickle in: $3,100 from the emergency room, $1,400 for imaging, $1,800 for twelve physical therapy visits. That’s $6,300. Signing the $4,000 release ended the driver’s right to claim more from that insurer, so the driver is $2,300 short.
2.42 million people were injured in U.S. traffic crashes in 2024, according to NHTSA. A release signed in the first week applies to bills that arrive in the third month.
What to say on that first call, and what to leave out
You can be courteous and brief at the same time. You have a contract with your own insurer, and it requires you to report the crash and cooperate. You don’t have one with the other driver’s company. In general you aren’t required to give that company a recorded statement, and the Illinois bar’s guide notes that you have the right to consult a lawyer before making any statement.
Fine to say
Better left unsaid for now
Your name, address and phone number
“It was my fault” or “I didn’t see him”
The date, time and location of the crash
“I’m fine” or “I’m not hurt”
The vehicles involved and your insurer’s name
Guesses about speed, distance or timing
Where your car is, so it can be inspected
Details of your medical history
“I’m still being evaluated. I’ll send records when treatment is done.”
“Sure, you can record this”
“Please send that to me in writing.”
“That amount sounds okay”
Why single out “I’m fine”? On a recorded line it turns into a statement about your injuries, made before a doctor has seen you. A neutral answer is accurate and costs nothing: “I’m getting checked out.”
If the adjuster keeps pushing for a recorded statement, say you’ll provide information in writing. And if fault’s in dispute or you were hurt, this is one of the moments when a short talk with an attorney, before any statement, can be worth the time.
Why does the offer come so fast?
A fast offer isn’t always a bad one. After a minor crash with car damage only, a quick settlement can be fair and convenient, because property damage can be counted the same week: the repair estimate, the rental bill and the tow.
Injuries are different, since in week one nobody knows the total. Emergency rooms, radiology groups, ambulance companies and physical therapists bill separately and on their own schedules, some bills take weeks to reach you, and follow-up care may not even be booked yet.
The Texas Department of Insurance tells people settling a claim that includes medical costs to talk with their doctor about any future treatment they might need before accepting. The reason is the release. The insurer will ask you to sign one, and a signed release blocks any future claim from that accident.
A release is a contract that ends the claim, and if the bills later run past the check, the difference is yours. You can’t reopen it because the number turned out to be wrong.
And the papers that close a claim don’t always say “release” at the top. Three kinds are worth knowing on sight.
Continued
Three things not to sign in a hurry
The first is a release of all claims. Any document with the words “release,” “full and final settlement” or “in full satisfaction” ends your claim. Say you’ve got a property damage claim and an injury claim from the same crash. Settling the car first and leaving the injury claim open is common, but the paperwork has to say that. Check whether it applies only to the car or to everything.
Then there’s the medical authorization. The other driver’s insurer needs records related to the crash. It doesn’t need your whole medical history, and a blanket authorization can open years of it. You’ve got two ways around that: offer to send the relevant records and bills yourself, or ask that the form be limited to providers who treated you for this crash and to dates after it.
The third one shows up in an envelope. A check can carry settlement language on the front, on the back or in the cover letter, and if “full and final” appears anywhere, depositing it can be treated as accepting those terms. Read all three before you deposit anything.
Related searches
Expecting a payment for the car only, and the wording’s unclear? Ask the adjuster to confirm in writing what the check covers.
Your first 30 days, step by step
If you have any symptoms, get a medical evaluation promptly. That’s a health decision first. It also starts the paper trail.
Report the crash to your own insurer right away, even if the other driver was at fault. Your policy requires it, and your own coverage may pay first for medical bills or repairs.
Request a copy of the police report as soon as it’s available and check it for mistakes in names, vehicle positions and insurance details.
Put everything in one folder: photos of both vehicles and the scene, witness names and numbers, the claim number, every bill and every explanation of benefits (the statement your health plan or Medicare sends after a claim). Pharmacy receipts and mileage to appointments go in there, too.
Missed work counts, so keep pay stubs and a note from your employer showing the days you were out. Retired? Note any paid help you needed, such as rides or home assistance, and keep those receipts.
Log every call with the date, the adjuster’s name and what was said, and follow up anything important by email so there’s a record.
The car can usually be settled on its own. Property damage doesn’t have to wait for the injury claim. Just check that the paperwork is limited to the vehicle.
The injury settlement is a different story. Hold off until treatment’s finished or your doctor can describe what’s still ahead, then add up the bills, the lost income and the out-of-pocket costs. That total is the floor for a serious conversation.
Ask for every offer in writing, with a breakdown of what it covers. If the injury offer comes in under your total, answer in writing, too: state the total, attach copies of the bills and ask the adjuster to explain anything left out.
So who pays the medical bills while you wait?
Nobody expects you to sit on the hospital bills until the claim settles. Who pays first comes down to two things, your state and the coverage you bought.
The state part first. There are twelve no-fault states, by the Insurance Information Institute’s count, and you’ll recognize the big ones: Florida, New York, New Jersey, Pennsylvania, Michigan and Massachusetts. Rounding out the list are Hawaii, Kansas, Kentucky, Minnesota, North Dakota and Utah.
If you’re in one of those twelve, your medical bills go first to your own personal injury protection, often listed as PIP on the policy. Who caused the crash doesn’t matter for that. What you give up is part of your right to sue the other driver, which is limited unless your injuries meet a threshold set by state law.
Three of the twelve bend that rule. In Kentucky, New Jersey and Pennsylvania, drivers can reject the limit and keep the full right to sue.
Everywhere else, the first money may come from optional medical payments coverage on your own auto policy, if you bought it. It would show up on the declarations page as “MedPay” or “medical payments.” Once that’s used up, or if you never had it, your health insurance pays the way it would for any other care.
What if you’re on Medicare? Medicare can step in and pay for crash-related care when the insurer responsible for the crash doesn’t pay promptly. Those are conditional payments, though. Once a settlement, judgment or award comes through, “Medicare is entitled to be repaid” for what it covered, in the words of the Centers for Medicare & Medicaid Services. You’re expected to report the claim to the Benefits Coordination & Recovery Center, at 1-855-798-2627.
Settle without accounting for that and part of your check may already belong to Medicare. Private health plans often have similar reimbursement rights.
The deadlines that do matter
“This offer is good until Friday” is a negotiating position. A legal deadline is something else, and it doesn’t bend.
Every state sets a time limit for filing an injury lawsuit, the statute of limitations, and the limits vary. How long do you get in California? Two years from the date of injury for personal injury, according to the state courts’ self-help guide, and three years for property damage. Other states allow less time or more; search your state court system’s self-help site for “statute of limitations” to find yours.
Government vehicles are their own trap. A claim against a city bus, a state vehicle or any other agency runs on a much shorter clock, with extra notice rules, and the California courts’ guide warns that it has to be presented to the agency well before the usual lawsuit deadline. If a government vehicle was involved, look up your state’s rule in the first weeks, not the first year.
Your own policy has deadlines, too, especially for uninsured motorist and medical payments claims. They’re easy to overlook because they sit in the “duties after an accident or loss” section, which almost nobody reads until a claim gets denied for late notice.
When is a lawyer worth calling?
Plenty of claims don’t need one. If only your car was damaged, or your injuries were minor and you recovered fully within a few weeks, you can usually handle the claim yourself. A fight over what the car was worth can go to small claims court; in Texas, the insurance department notes that Justice Court hears claims under $20,000 and you don’t need an attorney.
The picture changes with a serious injury: you were hospitalized, you need surgery or ongoing treatment, or you may have lasting limitations. So does a fault dispute, whether the insurer denies fault outright or says you were partly to blame, and so does an offer that came before your treatment ended from an adjuster who won’t wait. A lawyer is also worth a call when:
Medicare, Medicaid or a health plan wants reimbursement from the settlement;
the at-fault driver was uninsured or had low limits (the most their policy will pay), so your own policy comes into play;
more than two vehicles were involved, or a commercial or government vehicle was.
What does it cost? Most personal injury attorneys work on contingency. They’re paid a percentage of what’s recovered, and nothing if there’s no recovery. Your contract sets the percentage, and in some states bar rules cap it. In Florida, if the case settles before the defendant files an answer (its formal written response to the lawsuit), the cap is 33⅓% of a recovery up to $1 million. Once the answer has been filed, that cap rises to 40%. Case costs such as filing fees and expert witnesses are separate, and the Florida Bar warns that if your agreement says so, you may owe them even if you lose.
First consultations are commonly free, and I’d use one before signing anything on an injury claim that’s still being treated. Bring the folder. Ask plainly what the fee percentage is, who pays costs if you lose and who’ll handle your file day to day. Then ask if you need a lawyer for this at all. A good one will tell you when you don’t, and no attorney can honestly promise a result or a dollar figure in a first meeting.
Be just as wary of online settlement calculators. Many just multiply medical bills by a factor. Insurers don’t publish any formula, and the facts of your case count for more than a multiplier. A calculator can help you organize your numbers. It can’t tell you what your claim’s worth.
Before any call with an adjuster, put three things on the table in front of you: the claim number, the folder of bills, and a note that says “in writing, please.”
Home and auto insurance, escrow and mortgages, car loans, debt, credit and taxes
Edited by
The Moneystretching editorial team. A human editor checks every figure, date and rule against the sources before an article is published. How we check articles
Sources
NHTSA, Texas Department of Insurance, Illinois State Bar Association, Insurance Information Institute, CMS, California Courts, The Florida Bar. Full list with links
Updated Sep 29, 2026 · Reviewed against NHTSA, Texas Department of Insurance, Illinois State Bar Association, Insurance Information Institute, CMS, California Courts, The Florida Bar
Related searches
This article is general information, not financial, legal, tax, insurance or medical advice, and it is not a substitute for the advice of an attorney.
Up next on this topic
Picked to go with this article. Each one opens in a new tab.